When: Friday, October 30, 1:00 PM
Where: Tyler 106
Abstract
Asset-backed securities (ABS) play a vital role in financing American consumer automobile debt. Recently, economic analysis into ABS has benefited from the public release of data, which provides a new, rich source of loan level consumer auto loan information. Because this loan lifetime data is discrete-time and subject to random left-truncation, however, it is nontrivial to analyze. This has attracted recent study, but there is still no suitable approach to model this ABS loan lifetime data that incorporates regression coefficients for the lifetime of interest. We thus generalize the conditional, bivariate distribution to link to covariates, while keeping the left-truncation distribution unspecified. We solve the high-dimensional, constrained likelihood-based parameter estimation problem numerically, using a block coordinate descent design. Under suitable regularity conditions, we provide the complete large sample, multivariate normal distribution of the estimators. This allows for large sample inference into variable and model selection. We prove all results, verify with simulation, and generalize for right-censoring. We then apply our methods in an economic study of borrower prepayment behavior for 19,772 consumer auto loans from the 2017-3 Ally Auto Receivables Trust ABS bond. We find borrowers with pick-up trucks prepay more slowly, all else equal, among other consumer finance insights.
Bio
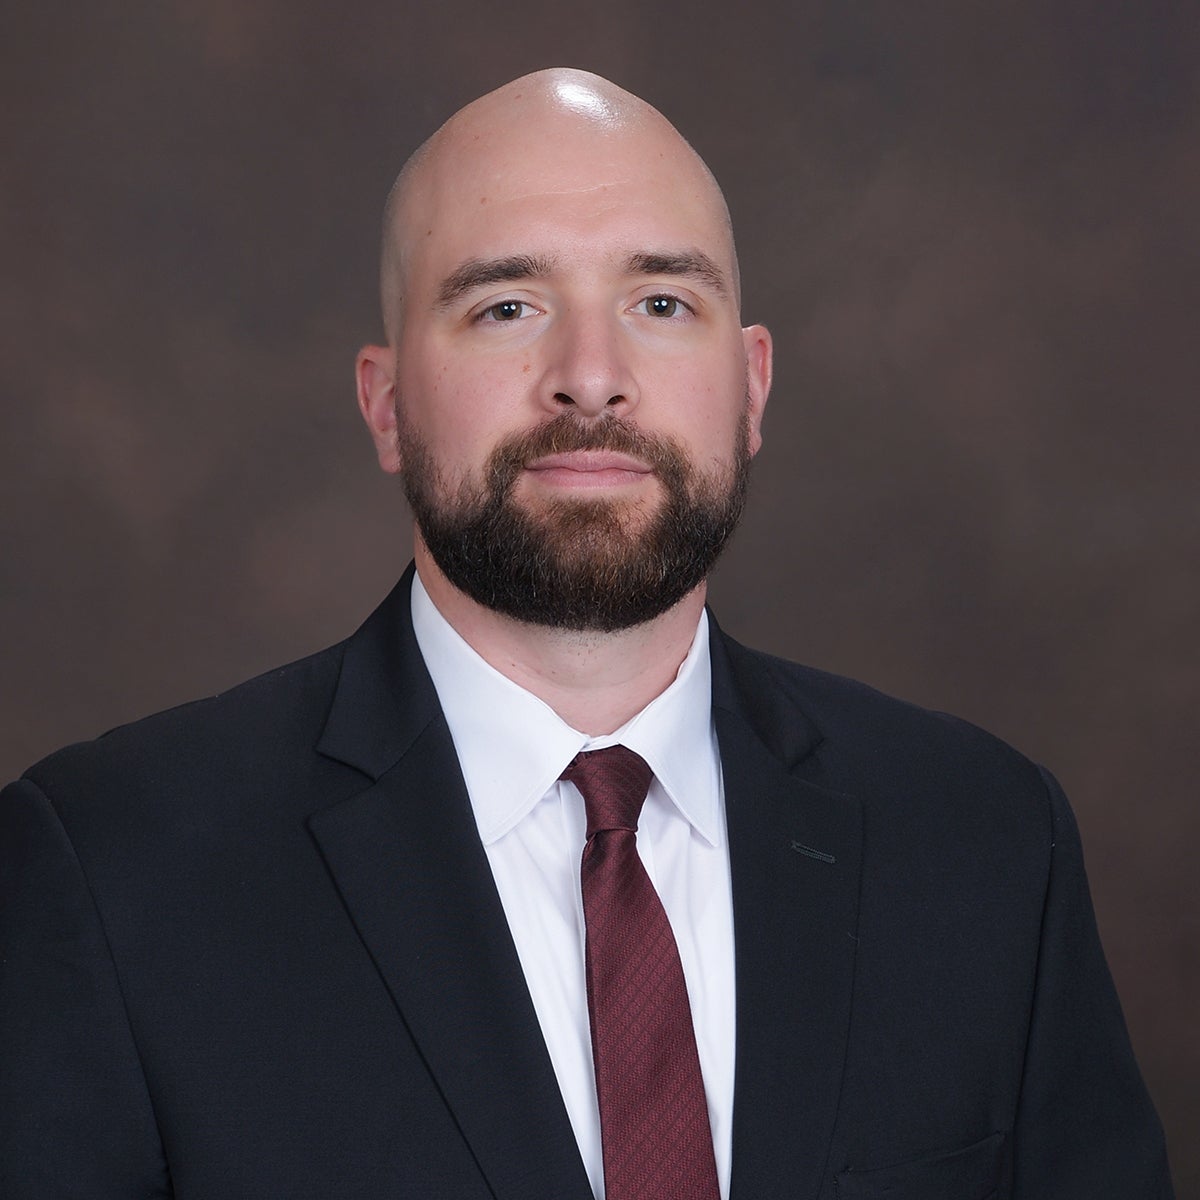
Jackson P. Lautier is an Assistant Professor in the Department of Mathematical Sciences at Bentley University. Prior to Bentley, Jackson spent nearly 10 years working at Prudential Financial, Inc. as an actuary in various roles, including risk management, investment strategy, and quantitative finance. Jackson is a Fellow of the Society of Actuaries, a Chartered Enterprise Risk Analyst, and a Member of the American Academy of Actuaries. He holds a PhD in Statistics and a BA in Mathematics/Actuarial Science, each from the University of Connecticut.